

Imagine walking into a restaurant and finding the AI industry hosting a very enthusiastic dinner.

It has ordered data centers, chips, cooling systems, power lines, construction workers and enough electricity to make the kitchen staff slightly nervous. Apparently, the cloud has a very physical shopping list.
The US government is already sitting at another table with a large tab of its own. Before dessert arrives, the headlines begin mixing the two bills together. AI is borrowing, America is borrowing, your job is apparently disappearing, and your electricity bill is going up. So everyone panics.
But this is exactly where we need to slow down.
The AI boom does have a bill and some of it can reach ordinary people (like you). But it does not arrive in one envelope marked dear taxpayer, good luck.
It travels through different routes: company profits, investors, interest rates, electricity prices, product prices and, possibly, the labor market (tracking becomes a real challenge). Some of those routes are already visible in the data. Others are still hypotheses wearing very confident headlines.
So, instead of asking whether AI is good or bad for the economy (a tiny question for an afternoon), let’s follow the invoice.
First: how large is the order?
The OECD estimates that nine large technology companies could spend $4.1 trillion on capital investment between 2026 and 2030. Major hyperscalers issued $122 billion in bonds in 2025, while AI-related private-credit transactions reached $59 billion.
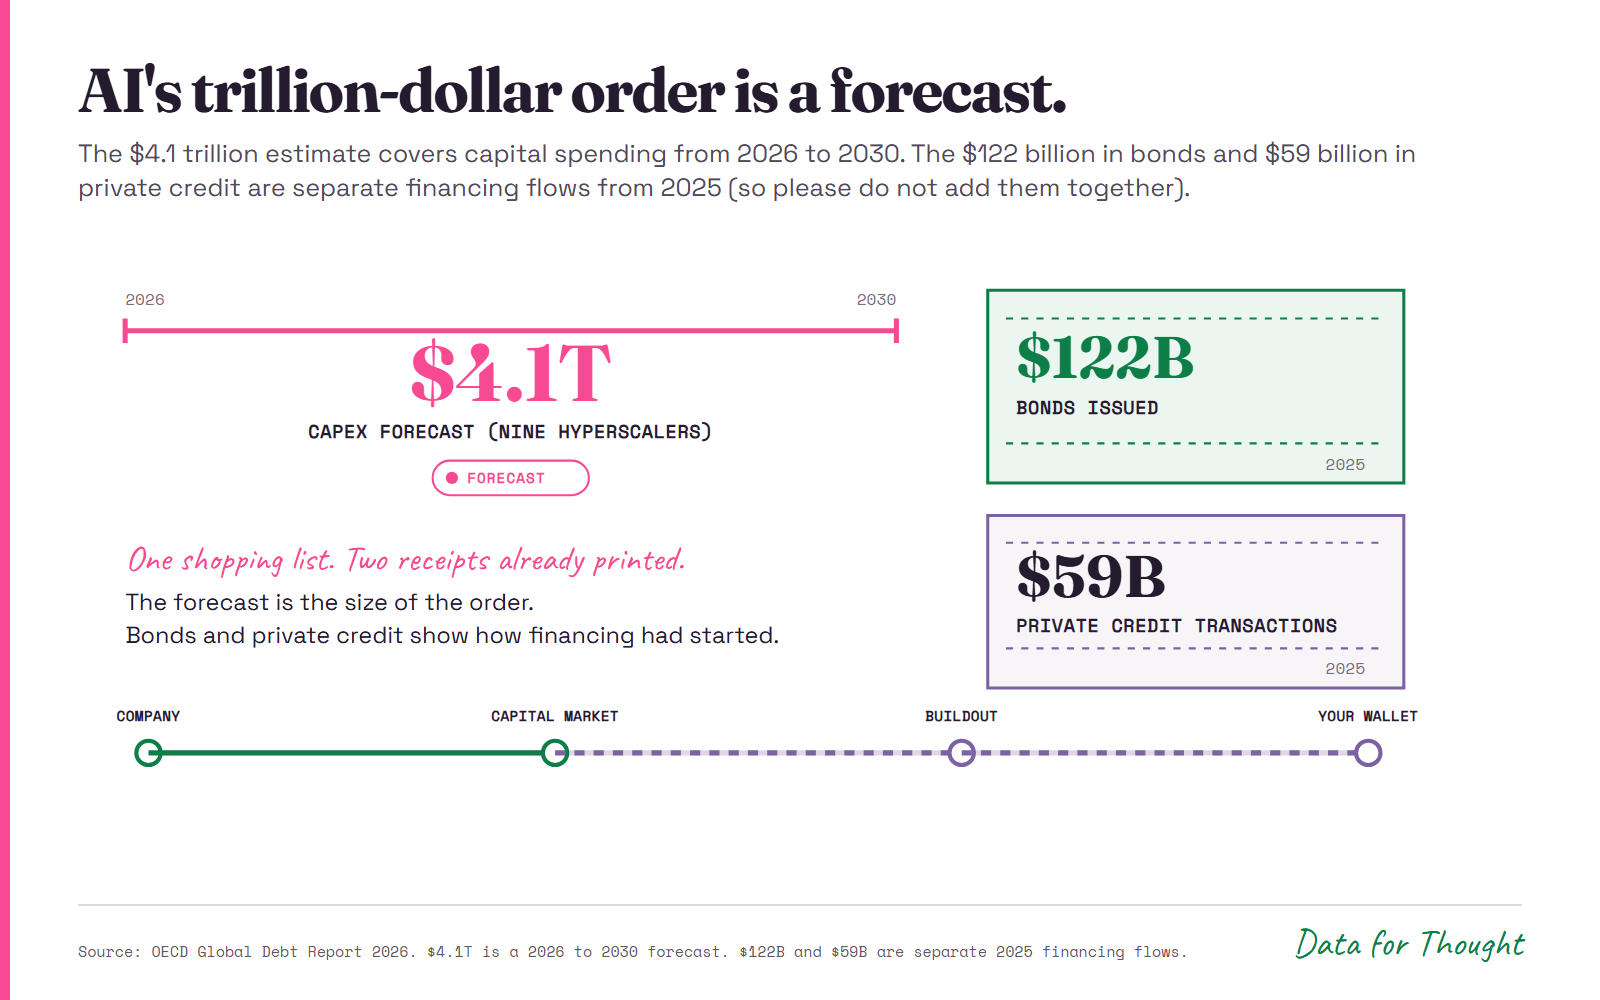
Figure 1. These numbers describe different things: a five-year spending forecast, one year of bond issuance and one year of private-credit transactions. Please do not add them together and create a $4.281 trillion monster. Source: OECD Global Debt Report 2026.
Let’s be clear on one important thing: the $4.1 trillion is an expected order, not a cheque that has already cleared. The other two numbers show ways companies are beginning to finance the buildout.
For now, the first people paying are the companies themselves and the investors funding them. Shareholders pay when cash is spent, or new shares dilute their ownership. Creditors take the risk that projects may not produce enough cash later. Customers may pay if companies raise prices.
This is not yet a taxpayer story. A company borrowing money does not magically turn its bond into US government debt (finance has not become that creative). A public bill appears only if policy builds a bridge through subsidies, guarantees, tax breaks, or a rescue.
Still, you have to pay attention to the (huge) scale of this AI investing. Once an investment wave becomes this large, it starts competing for things the rest of the economy also needs, like capital, electricity, grid equipment, metals and skilled workers.
That is where the invoice begins to travel.
The clearest route to your wallet may be the power socket
The newest estimate from Lawrence Berkeley National Laboratory puts US data-center electricity use at 11.8% of total electricity by 2030, with scenarios ranging from 9.5% to 15.3% (small reminder: in 2023, the share was 4.4%).
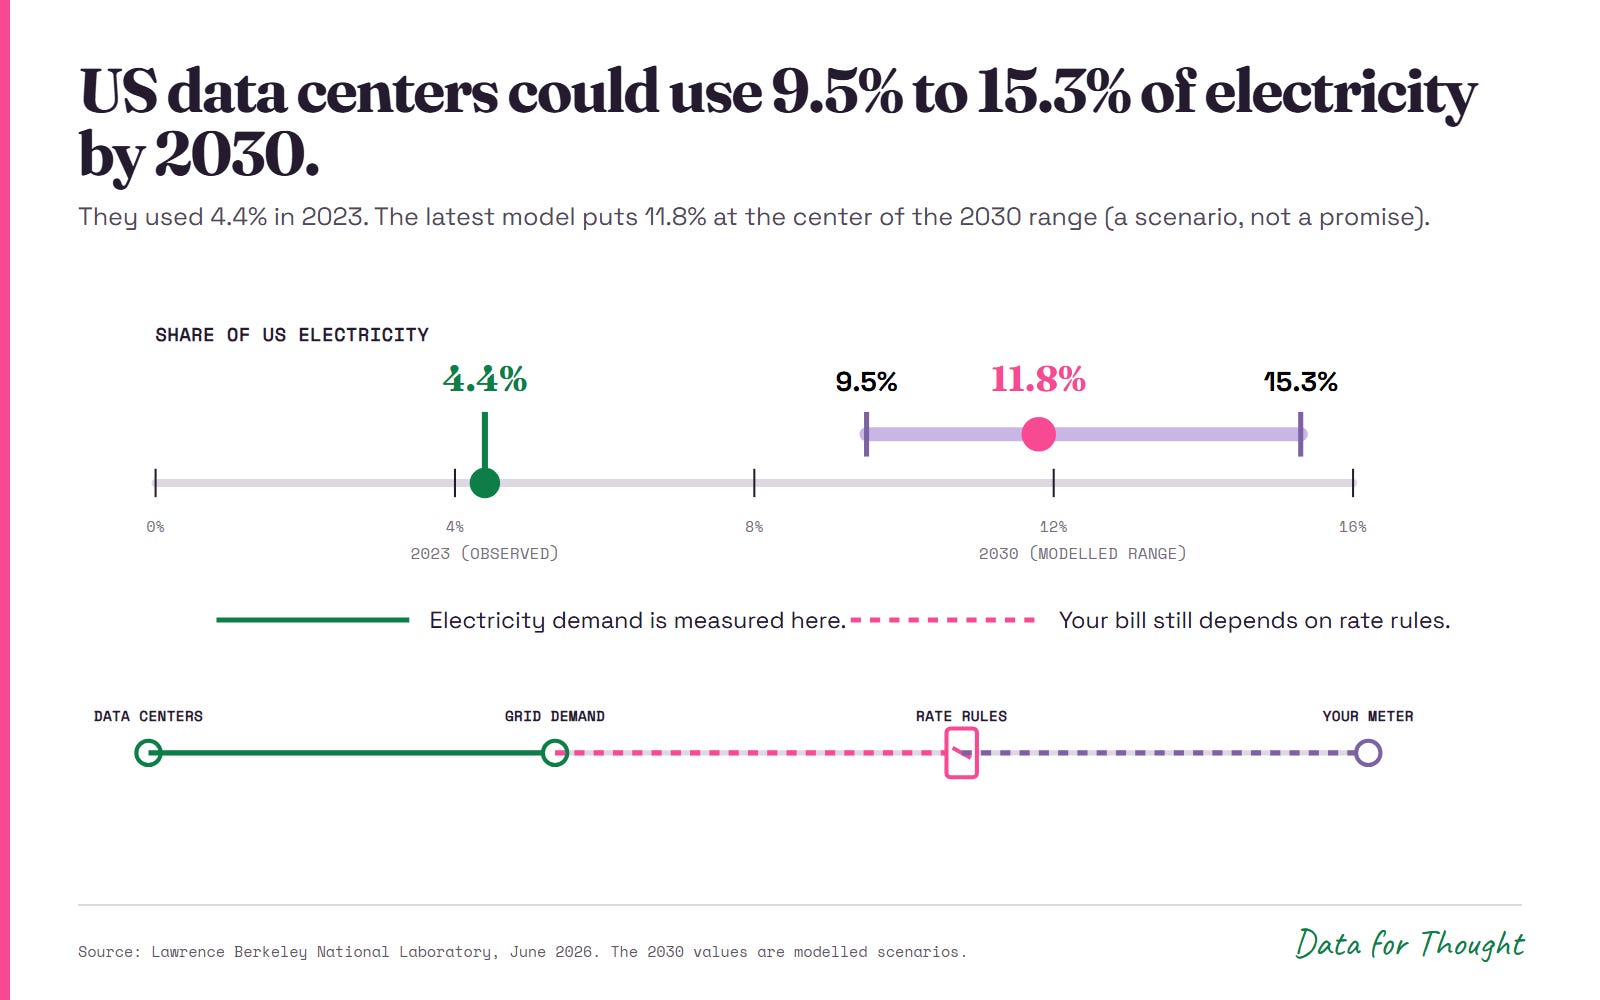
Figure 2. The 2030 number is a modelled scenario, not destiny. It changes with equipment shipments, chip efficiency, server use and cooling. Source: Lawrence Berkeley National Laboratory, June 2026.
Before panicking, this does not mean your electricity bill will also rise by 11.8%, since electricity consumption and electricity prices are not the same thing. But a new MIT study gives us a stronger clue about the route between the two. Looking at data-center entry between 2010 and 2024, the researchers estimate an average 2.7% increase in retail electricity prices (the breakdown reads as: residential effect of 2.1% and industrial effect of 4.2%).
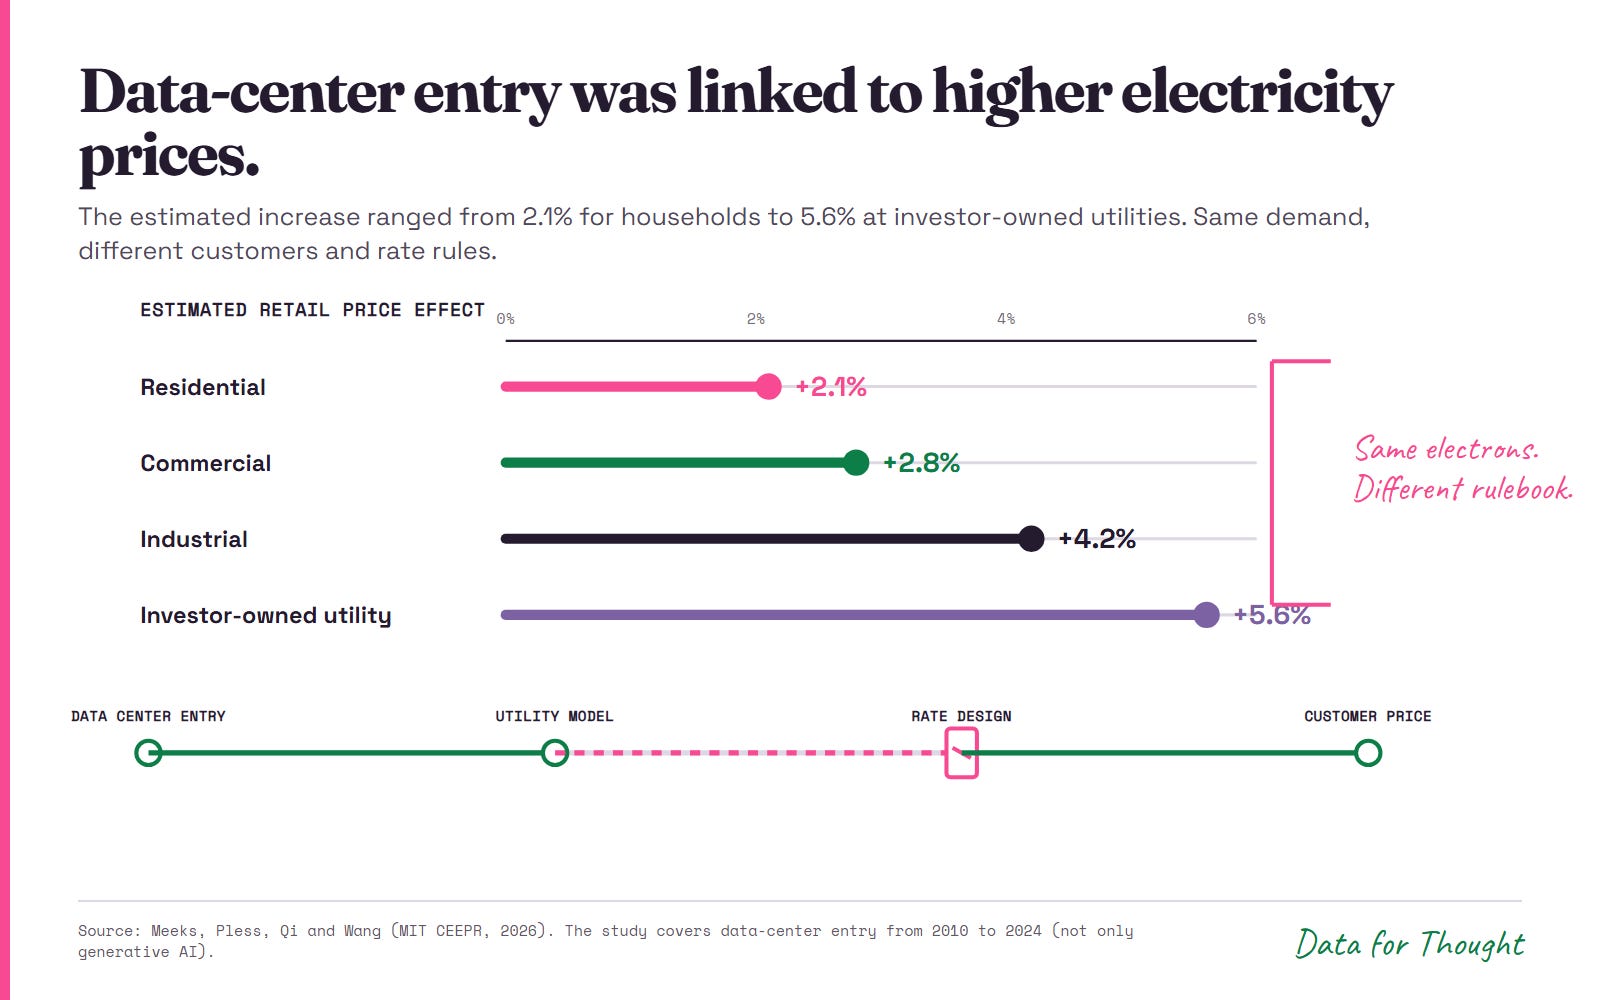
Figure 3. The study covers data centers broadly, not only generative-AI facilities. Effects also differed by utility ownership and regulation. Source: MIT CEEPR, 2026.
Again, you need to follow the chain, as a data center does not send you a personal Venmo request. Costs move through utility rules: who pays for a new substation, who signs a long-term contract, whether large users get special rates and how grid investments are divided among customers.
In other words, the technology creates the demand, but ultimately it is institutions’ job to decide who receives the bill. Of all the routes in this story, this is currently the most measurable household link.
Your paycheck is a quieter route (and a much harder one to prove)
Let’s dive into this rabbit hole.
The latest US jobs report was weak. Payroll employment fell by 23,000 in July, and the May and June estimates were revised down by a combined 103,000. Job openings were 7.4 million in June. The unemployment rate, however, remained relatively low at 4.1%, and average hourly earnings were 3.2% higher than a year earlier.
That combination looks less like a trapdoor opening under the labor market and more like a room slowly losing oxygen. Companies are not firing everyone, but they are hiring with less enthusiasm.
This can matter for your salary before it matters for your job. When there are fewer open roles, workers have fewer outside options. Fewer outside options can mean less bargaining power when asking for a raise or walking away from a bad offer.
Is AI causing the slowdown? While the signal is real, there is no way (based on the data) to pinpoint the cause.
The evidence is mixed because researchers are looking at different workers, different countries and different outcomes.
Stanford’s latest indicators find only modest differences across AI-exposure groups overall, but a more noticeable pattern among workers aged 22 to 25 (early-career employment has been weaker in more AI-exposed occupations). At the same time, Yale’s Budget Lab, using a method designed to make exposed and unexposed US occupations more comparable, finds no clear AI-related effect on employment or wages so far. A Danish study using administrative records finds substantial changes in tasks and AI adoption, but rules out average effects larger than 2% on earnings or hours during the first two years.
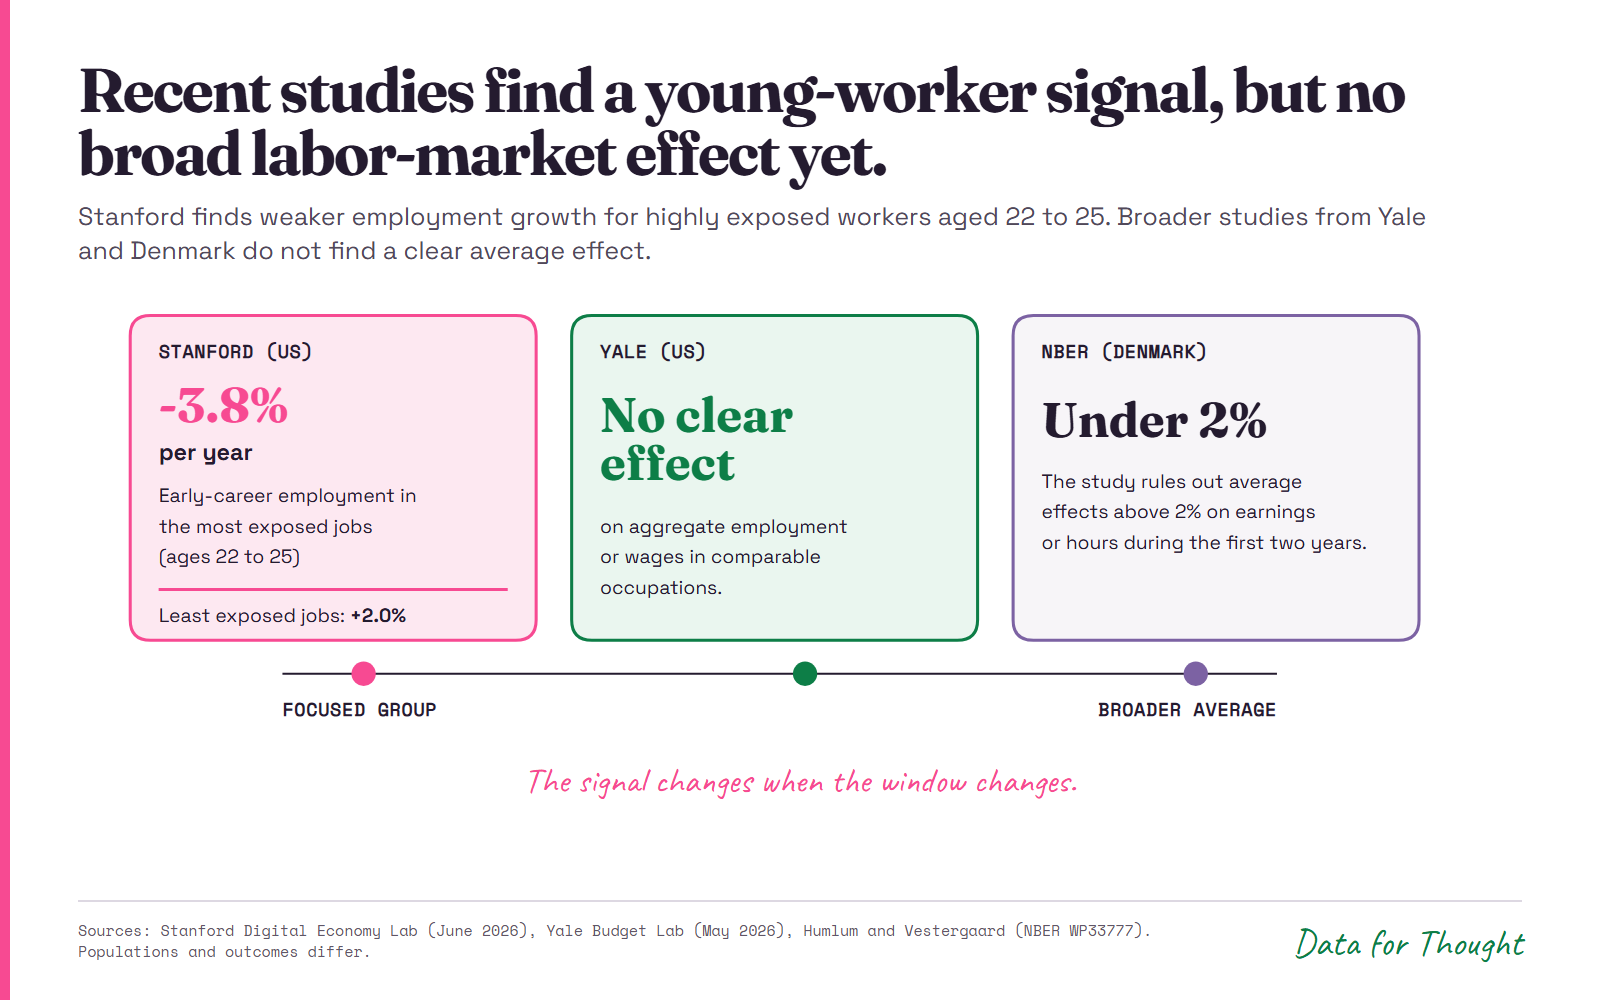
Figure 4. A concentrated early-career signal can coexist with no clear economy-wide effect. Sources: Stanford Digital Economy Lab, Yale Budget Lab and Humlum & Vestergaard, NBER.
Not the clean answer the internet ordered, I know.
But conflicting results are not useless because they tell us where to look. If AI is affecting work first through entry-level hiring, task reorganisation or a few highly exposed occupations, the aggregate jobs number may be the last place where the change becomes obvious.
The honest conclusion today is narrower: the labor market is cooling; some early-career patterns deserve attention; AI is one possible mechanism; the published data cannot assign it the blame.
Productivity may hide the distribution of costs
Another set of numbers arrived in the same week and can help us sort the way through this bill. US nonfarm business productivity was 2.2% higher than a year earlier. Real hourly compensation was 0.1% lower, and labor’s share of business output fell to 52.9%, the lowest level in a series beginning in 1947.
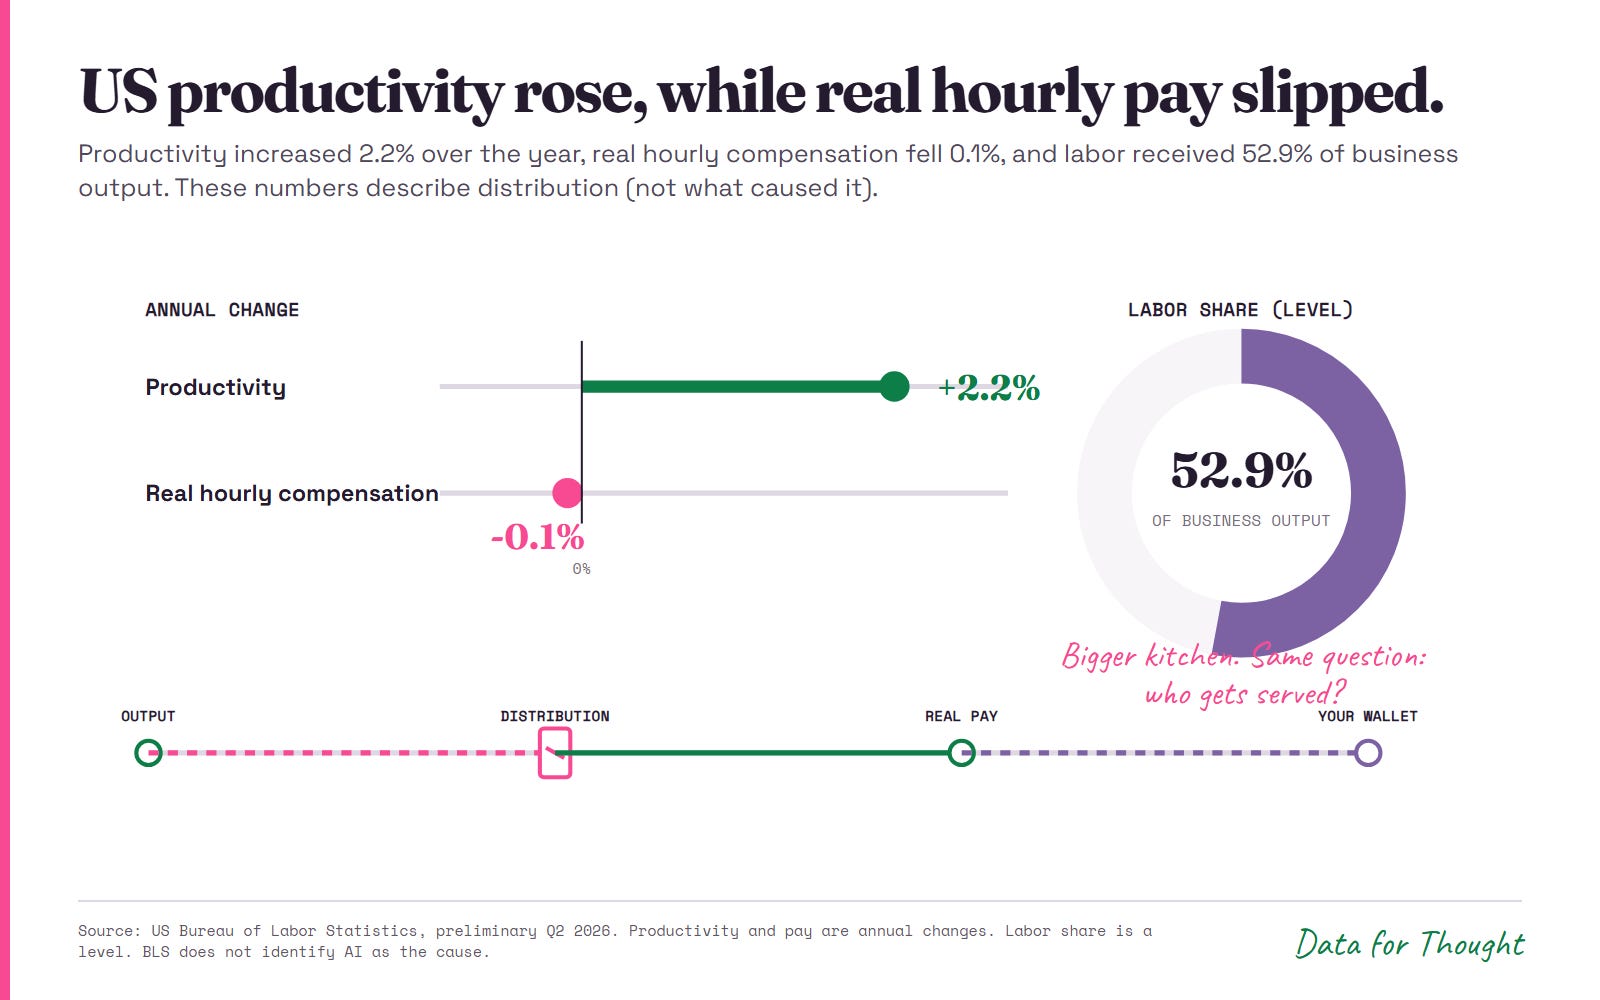
Figure 5. Productivity and real compensation are annual changes; labor share is a level. The BLS release does not identify AI as the cause of any of them. Source: US Bureau of Labor Statistics, Q2 2026.
Let me repeat the boring-but-essential part: we cannot infer that AI caused this productivity growth or the fall in labor share (the data do not identify any cause).
What the numbers give us is a distribution question.
If AI eventually helps businesses produce more per hour, who captures the gain? Workers through higher pay? Consumers through lower prices? Owners through higher profits? Or a little of each?
The main sequence of thoughts here may be: Productivity tells us the pie can grow -> Labor share tells us to check who received the slice.
It is too early to make any conclusions, and these two are different questions (any serious AI discussion needs both).
The two debt tabs are separate, but they use the same credit card machine
Now back to the other table in our restaurant, where you need to understand first that: corporate AI debt and US government debt remain separate liabilities. Alphabet (parent holding company of Google) must repay Alphabet’s creditors. The Treasury must repay Treasury investors. There is no accounting shortcut that combines them…. Buttttt both borrow in the same capital market.
The Dallas Federal Reserve estimates that AI-related investment-grade bond issuance could be around $300 billion in 2026. Because much of it has long maturities, it could add up to $360 billion in ten-year-equivalent duration, roughly one-eighth of the duration supplied by US Treasury issuance.
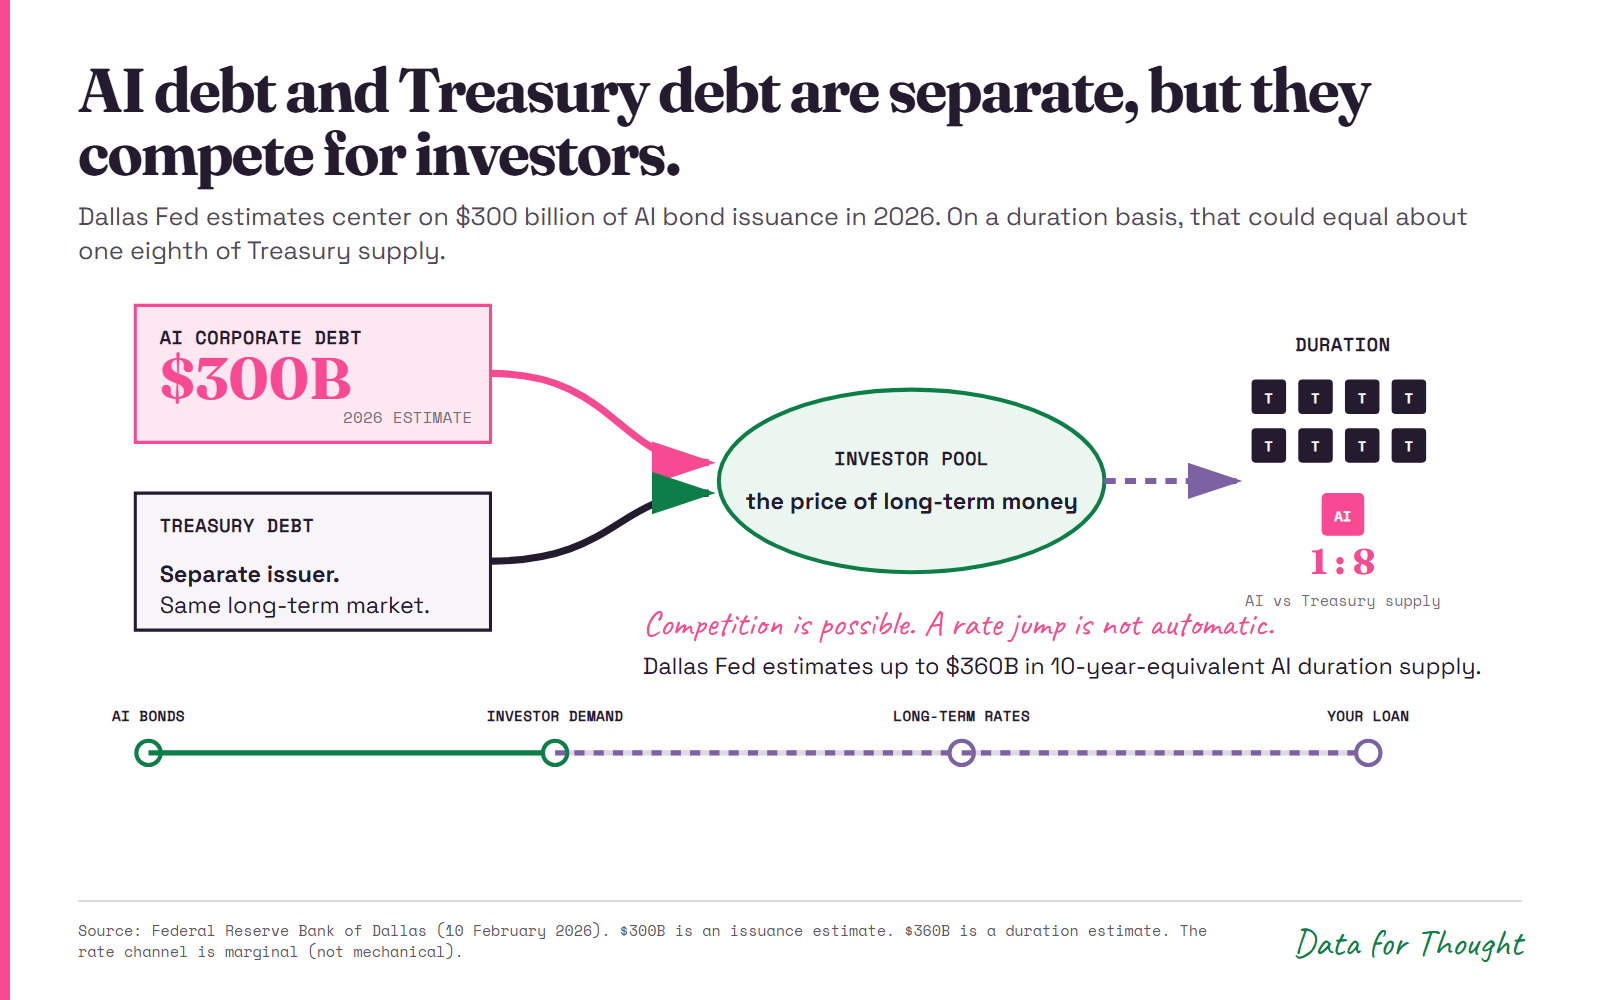
Figure 6. Separate debts can still compete for investors. The interest-rate effect is a possible marginal channel, not a one-for-one mechanical result. Source: Federal Reserve Bank of Dallas.
In normal-person language: if investors are asked to absorb much more long-term debt, they may demand a slightly better return. That can put upward pressure on long-term borrowing costs at the margin.
Will your mortgage rate jump because one technology company issued a bond? No. Interest rates move for many reasons: inflation, central-bank policy, growth expectations, Treasury supply and global demand for safe assets. AI financing becomes one more person crowding around the same credit card machine.
While there is still a real connection here, the effect size of this demand is nowhere to be found in the data (yet).
So, who is paying?
The annoying economist answer is: different people, through different mechanisms, at different times.
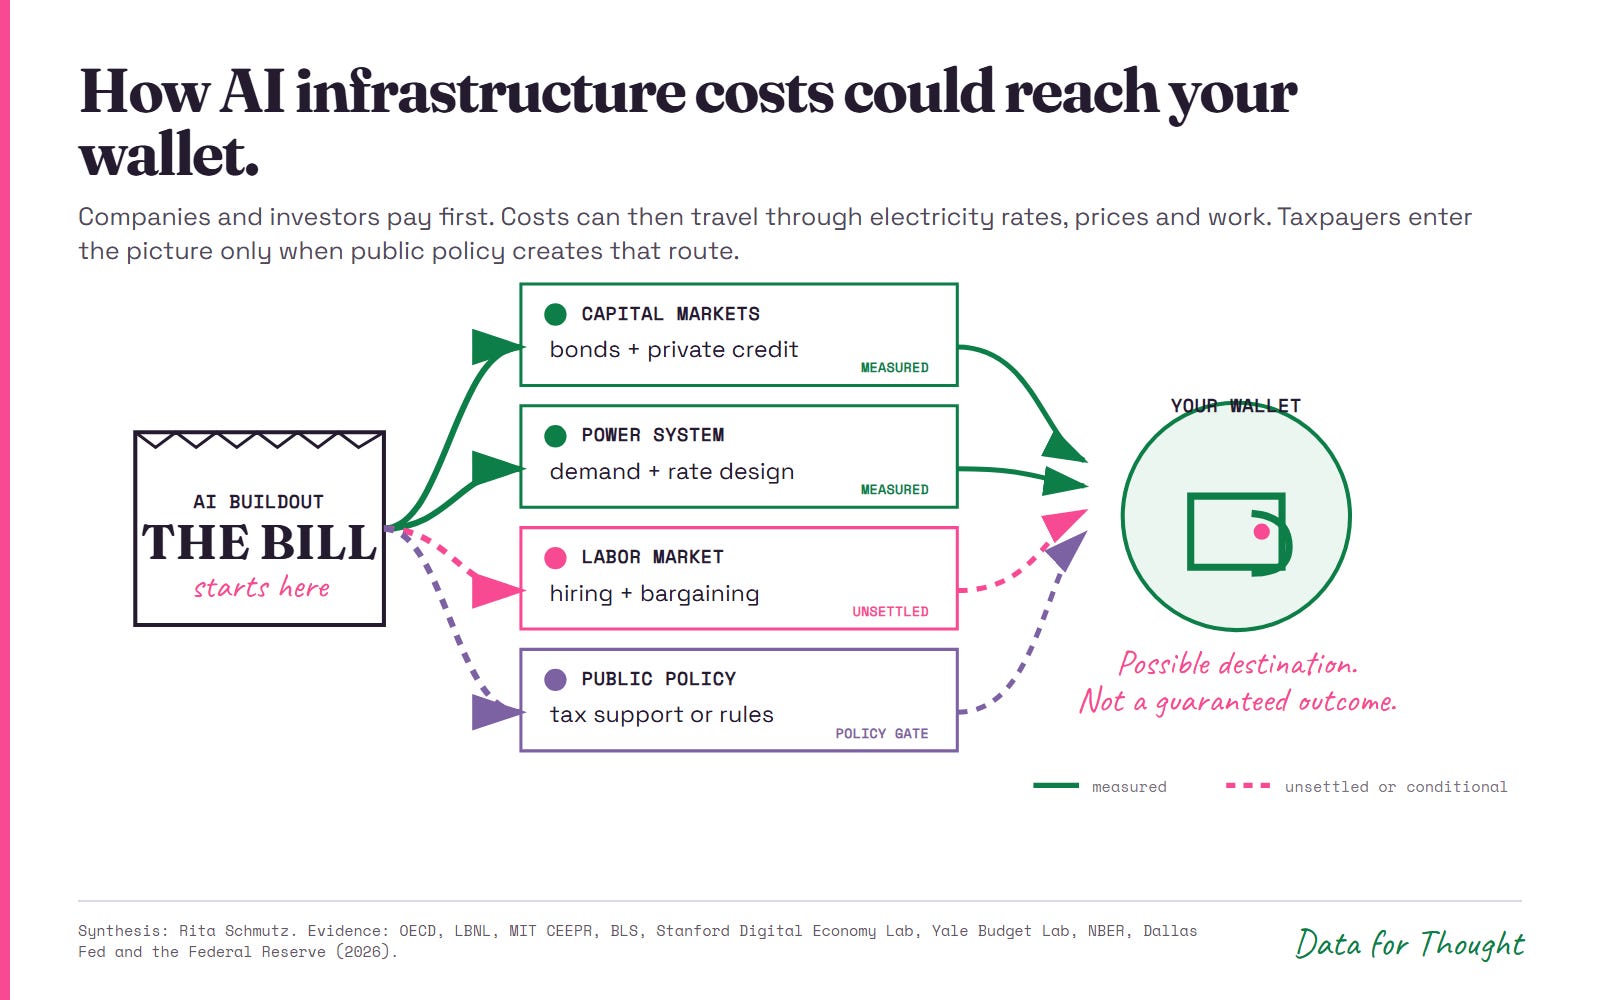
Figure 7. A route is not proof that the cost has already arrived. This map shows what evidence we should look for next.
Right now:
Shareholders and creditors are financing much of the buildout and own the first layer of risk.
Electricity customers can pay when grid and generation costs are passed through rates. This is the clearest measured household route.
Workers may feel pressure through hiring and bargaining power, but we cannot yet isolate an economy-wide AI effect.
AI customers may pay through software and compute prices. The Federal Reserve already notes AI-related price pressure in software, computers, electronics and some industrial metals, although broader inflation also reflects energy, tariffs and supply constraints.
Taxpayers pay only when government policy creates a bridge to the public balance sheet.
The story I take from these numbers is not that AI is destroying all jobs (the data do not support that). It is also not that taxpayers are already funding the entire boom (the data does not support that either).
The more defensible conclusion is that the AI buildout has become large enough to touch several markets at once. It is increasing demand for electricity and physical infrastructure. It is bringing more corporate debt into a capital market already absorbing heavy government borrowing. It may be changing some entry-level work before showing up clearly in aggregate employment. If productivity gains arrive, the distribution of those gains will depend on bargaining power, competition, ownership and policy.
That is what we can construct from the data: the size of the order matters, but the mechanism decides who pays and who benefits.
So, before buying the next headline, I would ask four questions:
Is the number a forecast, a flow or a stock?
Who actually signed the bill?
What mechanism carries the cost from them to me?
Who owns the upside if the investment works?
The number tells you how big the dinner order is and following the invoice tells you whether it ever reaches your table.
That is the difference between reading data and building a thought from it.